


Environmental audits give organizations a systematic way to examine how their activities affect the environment. They compare existing conditions with agreed criteria, policies, legal requirements, baseline expectations, and management objectives.
They are useful because environmental programmes need regular assessment to confirm that controls work as intended. Audits can reveal weaknesses, environmental risks, inefficient practices, compliance gaps, and opportunities for improvement.
Environmental auditing developed from accounting audit practices, but its application now covers environmental management systems, regulatory compliance, operational activities, waste, energy, materials, pollution controls, environmental risk, resource efficiency, and sustainability.
The audit may involve internal employees, external auditors, or independent third-party specialists. The right choice depends on the organization’s objectives, required independence, available expertise, audit scope, applicable requirements, and assessment needs.
This article explains the major types and costs of environmental audits, their benefits, the audit process, essential report requirements, practical uses of findings, and important planning considerations for organizations across different sectors.
What Environmental Audits Mean
Environmental audits provide a structured way to compare existing environmental conditions and practices with defined criteria. They help organizations determine whether management controls work and whether environmental policies achieve intended results.
An audit examines evidence rather than relying only on assumptions. Auditors review records, procedures, observations, interviews, and relevant operational information to judge performance, identify weaknesses, and support better environmental management decisions.
The International Chamber of Commerce described environmental auditing as a systematic, documented, periodic, and objective management tool. Its purpose includes strengthening environmental management control and checking compliance with company and regulatory requirements.
ISO-oriented auditing also emphasizes systematic, independent, and documented processes for obtaining evidence. The evidence allows auditors to determine how closely an environmental management system meets established audit criteria and organizational requirements.
Environmental audits therefore support continuous improvement. They can verify compliance, evaluate management systems, assess risks from regulated or unregulated materials, and reveal cost-saving opportunities connected with environmental monitoring and resource use.
Read Also: Strategic Environmental Assessment
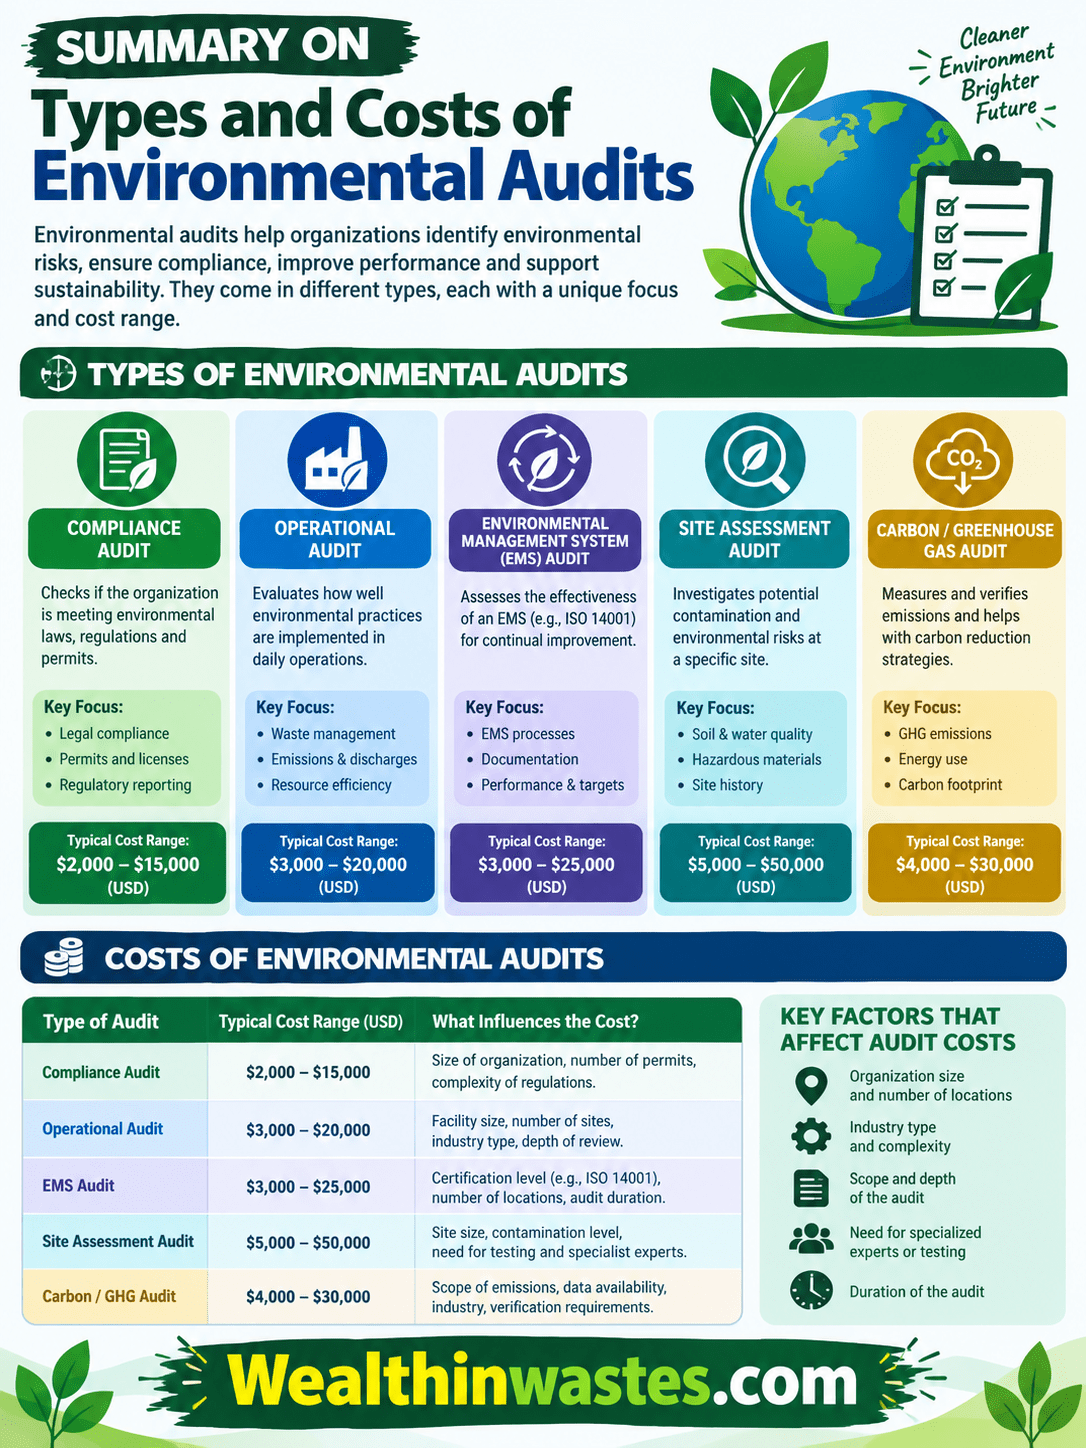
Types of Environmental Audits
1. Liability Audits: Liability audits identify conditions that could expose an organization to environmental responsibility, financial loss, legal action, cleanup obligations, or other consequences. They focus attention on present and potential sources of environmental liability.
2. Compliance Audits: Compliance audits check how well an organization meets applicable environmental regulations, permits, internal requirements, and other established criteria. They can identify gaps requiring corrective action before violations create larger operational or legal problems.
3. Environmental Risk Audits: Environmental risk audits examine processes and procedures for conditions that could create environmental harm. They help managers identify potential risks, evaluate existing controls, and prioritize improvements according to the seriousness of identified exposure.
4. Due Diligence Audits: Due diligence audits assess environmental liabilities before an organization purchases plants, equipment, property, or other operational assets. They can reveal hidden environmental problems that may affect investment decisions, responsibilities, and future costs.
5. Managerial Environment Audits: Managerial environment audits focus on management-related environmental issues. Common examples include environmental management system audits, environmental policy audits, and corporate audits that examine whether arrangements support stated environmental management principles.
6. Activity Audits: Activity audits concentrate on specific operations or environmental activities and examine both technical and management issues. Examples include product audits, waste audits, and energy audits covering defined waste streams and classifications.
Costs of Environmental Audits
1. Management And Staff Time: Management and staff spend working hours preparing documents, attending interviews, supplying evidence, responding to questions, and reviewing findings. This time creates an opportunity cost because employees may temporarily leave routine operational responsibilities.
2. Internal Auditor Training: Organizations may need to train internal auditors so they understand auditing methods, environmental requirements, evidence gathering, reporting, and objective assessment. Training costs can include instruction, materials, certification activities, travel, and employee time.
3. External Auditor Fees: External auditors or independent verifiers may charge professional fees for planning, site visits, evidence review, interviews, technical assessments, reporting, and follow-up work. Costs usually rise when the audit requires specialist expertise.
4. Operational Disruption: Audit activities can interrupt normal operations when personnel provide information, processes require observation, equipment needs inspection, or work areas require controlled access. The resulting disruption should form part of realistic audit budgeting.
5. Audit Preparation And Reporting: Organizations can incur expenses while collecting records, preparing facilities, organizing evidence, arranging meetings, documenting findings, and producing audit reports. Understanding waste minimization costs can also reveal resource losses that audits may uncover.
6. Corrective Action Costs: Hidden costs arise after findings require corrective action. Organizations may need repairs, new controls, improved waste handling, additional monitoring, employee training, equipment upgrades, or remediation activities to correct identified environmental control problems.
Benefits of Environmental Audits
Regular auditing helps organizations identify compliance weaknesses before regulators, customers, or other stakeholders discover them. Early action can reduce exposure to fines, remediation expenses, operational restrictions, and other costs associated with environmental non-compliance.
Environmental audits help organizations recognize risks created by processes, materials, equipment, and practices. Better risk visibility supports stronger controls, lowers exposure, and can contribute to improved conditions for environmental protection and sustainability.
Clear environmental information can strengthen relationships with employees, communities, regulators, investors, customers, and other stakeholders. Demonstrating responsible management may build goodwill, improve communication, and strengthen confidence in organizational practices and decisions.
Audit findings can reveal unnecessary waste, poor material use, inefficient processes, and avoidable resource losses. Corrective actions can improve material efficiency, reduce operating costs, support product quality, and strengthen waste reduction efforts.
Environmental audits create a recurring review mechanism for environmental management. Organizations can compare results over time, track corrective actions, assess whether controls remain effective, and support environmental pollution control through continuing improvement.
Environmental Audit Process
1. Audit Preparation: Preparation covers planning and organizing the audit. The organization defines objectives, scope, criteria, responsibilities, information needs, schedules, participants, supporting documents, practical arrangements, and communication procedures before auditors begin detailed fieldwork.
2. Facility Visit: The facility visit represents the audit proper. Auditors observe operations, inspect relevant areas, interview personnel, examine records, gather evidence, and compare actual practices with audit criteria, procedures, policies, and regulatory expectations.
3. Assessment And Reporting: Assessment and reporting involve reviewing evidence, evaluating findings, identifying gaps, and preparing the audit report. Follow-up activities then track agreed actions and determine whether identified weaknesses receive suitable corrective attention.
4. Evidence Review: During the process, auditors should base conclusions on reliable evidence gathered through observation, interviews, records, measurements, and other appropriate sources. Sound evidence strengthens the credibility and usefulness of audit findings about pollution and environmental conditions.
5. Follow-Up: Follow-up confirms whether responsible personnel have addressed findings according to agreed actions and deadlines. This stage turns audit observations into measurable improvements and supports the continuous improvement role of environmental auditing within environmental control arrangements.
Audit Report Requirements

1. Accuracy: Audit findings should reflect validated facts and contain no avoidable errors. Accurate reporting increases confidence in the audit and helps managers make decisions based on reliable evidence rather than assumptions or incomplete information.
2. Clarity: An audit report should communicate findings in straightforward language. Unnecessary jargon and excessively technical wording can reduce understanding, so writers should explain important issues clearly for managers and other intended readers.
3. Conciseness: Good reports remain focused and direct. They should present significant findings, supporting evidence, risks, corrective actions, and recommendations without unnecessary repetition, lengthy digressions, or information that does not support the audit purpose.
4. Timeliness: Timely reporting helps organizations respond while audit information remains current. The source recommends preparing a draft within one week after completion and finalizing the report within four or five weeks.
5. Balanced Tone: Professional reports should use simple English and avoid embellishment. A balanced tone presents findings objectively, distinguishes facts from opinions, and gives management enough information to understand issues without creating unnecessary confusion.
6. Essential Contents: A useful report can include a contents list, executive summary, audit purpose and scope, findings analysis, corrective-action references, recommendations, distribution details, audit-program records, and participant details for the environmental management programme.
7. Practical Length: The source material states that an environmental audit report should ideally remain within twenty-five pages. A focused report makes important findings easier to locate, understand, communicate, and use during follow-up environmental reviews.
How Organizations Use Audit Findings
Audit findings become valuable when managers convert observations into decisions and measurable actions. A finding can reveal a compliance gap, inefficient practice, environmental risk, or opportunity for better resource management.
Organizations can prioritize findings according to environmental significance, legal implications, operational consequences, available resources, and urgency. This approach helps management direct attention toward issues that require immediate control or further investigation.
Audits can also improve waste management decisions. Reviewing waste generation, handling, treatment, recycling, and disposal practices can expose avoidable losses and support more effective waste control measures across operational facilities.
Environmental performance often depends on accurate information about pollution sources and existing controls. Reviewing hazardous waste information can help teams connect findings with storage, handling, treatment, disposal, and compliance requirements.
Findings involving agricultural operations should consider waste from crops, livestock, processing, and chemical use. Reviewing agricultural waste characteristics can help auditors recognize environmental aspects relevant to farm and agro-industrial activities.
Industrial facilities may face specific effluent and contamination concerns. Reviewing industrial effluent impacts can help managers connect audit findings with water quality, pollution prevention, regulatory expectations, and stronger operational controls.
Read Also : Top Wastewater Management Companies in the World
Environmental Audit Planning Tips
Effective environmental audit planning starts with a clearly defined purpose. Managers should determine what they need to verify, which activities matter most, what criteria apply, and what evidence will demonstrate performance.
Scope should match the organization’s significant environmental aspects and practical needs. A focused audit can examine particular processes, while a broader programme may review management systems, facilities, waste streams, energy use, and compliance.
Auditors should prepare for environmental risks associated with hazardous materials. Reviewing hazardous waste controls can help teams develop suitable questions, evidence requirements, inspection priorities, and corrective-action expectations before fieldwork begins.
Planning should also consider disposal locations and their surrounding conditions. Reviewing landfill environmental impacts and site-selection factors can help auditors examine contamination pathways, community concerns, regulatory risks, and potential remediation requirements.
Water and wastewater activities may require detailed attention because contamination risks can cross facility boundaries. Relevant water waste management practices can strengthen audit preparation where water quality, treatment, discharge, or resource recovery matters.
Organizations should connect audit planning with resource recovery opportunities. Understanding recycling incentives can help auditors identify areas where environmental improvements may also reduce waste, conserve materials, and support economic efficiency.
Finally, managers should consider broader sustainability objectives when setting audit priorities. These priorities can help translate audit findings into practical improvement opportunities across daily operations, environmental goals, and long-term strategic planning.
Summary on Types and Costs of Environmental Audits
| Area | Key Points |
|---|---|
| Meaning | Systematic, documented and objective assessment of environmental performance against defined criteria. |
| Types | Liability, managerial environment and activity audits, including compliance, risk, due diligence, waste and energy audits. |
| Costs | Direct costs include staff time, training, external fees, disruption and reporting; hidden costs arise from corrective actions. |
| Benefits | Supports compliance, risk reduction, stakeholder confidence, environmental efficiency and continuous improvement. |
| Process | Audit preparation, facility visit, assessment and reporting, followed by corrective-action follow-up. |
| Report | Should be accurate, clear, concise, timely, objective, practical and focused on findings and actions. |
Frequently Asked Questions About Types and Costs of Environmental Audits: Complete Guide
1. What is an environmental audit?
An environmental audit is a systematic, documented, periodic, and objective evaluation used to assess environmental performance, verify requirements, identify risks, examine management controls, and support continuous environmental improvement within an organization.
2. What are the main types of environmental audits?
The source identifies liability audits, managerial environment audits, and activity audits. Liability work includes compliance, risk, and due diligence audits, while activity audits examine specific technical or operational areas within an organization.
3. What are direct environmental audit costs?
Direct costs include management and staff time, internal auditor training, external auditor fees, operational disruption, audit preparation, documentation, publishing, and other resources used while conducting the environmental assessment process.
4. What are hidden environmental audit costs?
Hidden costs arise when audit findings require corrective action. These expenses can include repairs, remediation, improved controls, additional monitoring, training, equipment upgrades, and changes to environmental management practices after the audit.
5. How many phases does an environmental audit have?
The source describes three major phases: audit preparation, facility visit, and assessment and reporting. Follow-up activities continue afterward to track corrective actions and confirm improvements across the organization.
6. What should an environmental audit report contain?
A report should contain the audit purpose and scope, findings, analysis, corrective-action references, recommendations, distribution details, programme records, participant information, and an executive summary for managers and other decision-makers.
7. Why do organizations conduct environmental audits?
Organizations conduct environmental audits to verify compliance, evaluate environmental management systems, assess risks, identify inefficiencies, reduce environmental impacts, improve resource use, and support informed management decisions across operations.
8. How often should environmental audits be performed?
Audit frequency depends on organizational needs, risks, requirements, and audit purpose. The source notes three-month liability auditing and differing compliance audit schedules for internal and external auditors.
Do you have any questions, suggestions, or contributions? If so, please feel free to use the comment box below to share your thoughts. We also encourage you to kindly share this information with others who might benefit from it. Since we can’t reach everyone at once, we truly appreciate your help in spreading the word. Thank you very much for your support and for sharing!
Read Also: Proper Farm Waste management guide